Rowan: The Meals-and-Lodging Tax Result and Its Statutory Limits Today
Rowan Companies, Inc. v. United States, 452 U.S. 247 (1981), held that regulations improperly included certain employer-provided meals and lodging in FICA and FUTA wages while excluding the same benefits from income-tax withholding wages. The Court read the substantially identical definitions then in force consistently. Congress later changed the framework. A current payroll analysis must use the express statutory exclusions and cannot assume that every withholding exclusion automatically controls employment taxes.
The Court concluded that “the Regulations are invalid” and explained that the Service erred in using them to include the employer-provided meals and lodging in wages 452 U.S. at 263.
Offshore working conditions explained the benefits
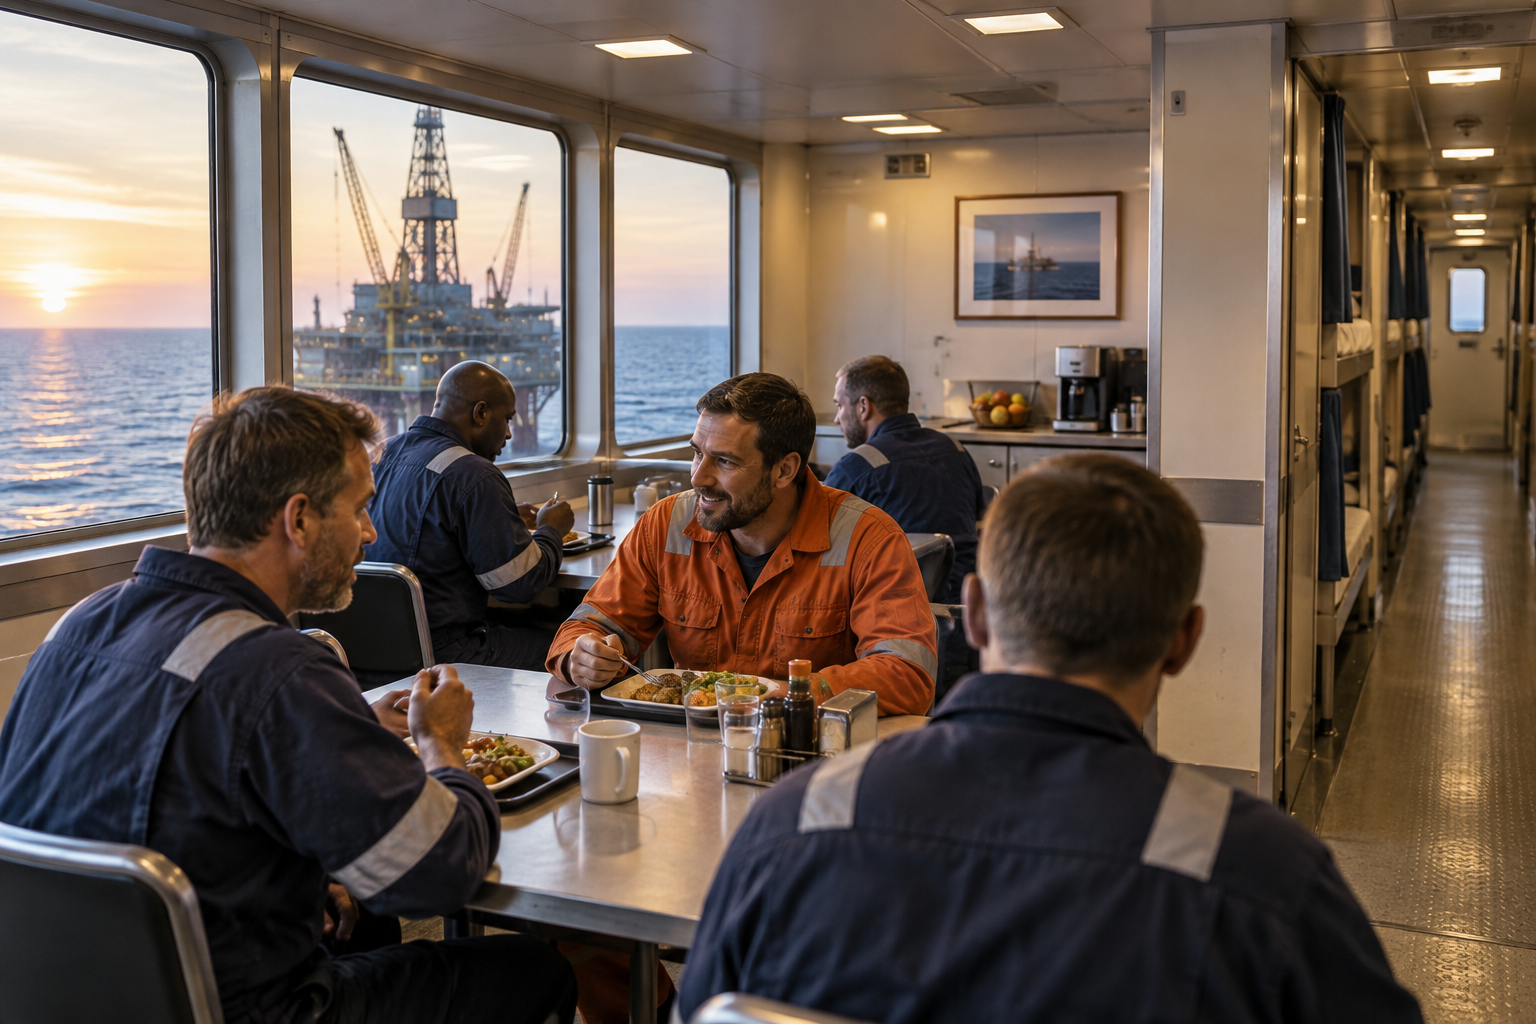
During the tax years at issue, Rowan operated offshore drilling rigs, some far from land. Employees worked extended tours and received meals and lodging rather than being transported ashore after every shift. They received no cash allowance for skipping meals, and the employer did not provide the same benefits during leave or at its land-based rigs. 452 U.S. at 248–249.
The employer excluded the benefits from wages for FICA, FUTA, and income-tax withholding. The IRS assessed employment taxes while accepting the withholding exclusion. Rowan paid and sued for a refund. The district court ruled for the government, and the Fifth Circuit affirmed based on the different purposes of the tax systems. The Supreme Court reversed.
The dispute concerned inconsistent wage definitions
The government acknowledged that the benefits satisfied section 119's convenience-of-the-employer requirements and were properly excluded from withholding wages. Its position on FICA and FUTA rested on regulations treating appreciable meals and lodging as remuneration. The Court examined whether that interpretation reasonably implemented Congress's definitions. 452 U.S. at 250–253.
The majority relied on the similar statutory wording, legislative history, and the administrative simplicity of consistent wage treatment. It distinguished “income” from “wages” rather than assuming the concepts always coincide. The Court also examined the development and consistency of the Treasury positions instead of treating their existence alone as conclusive. 452 U.S. at 254–262.
The holding was tied to the statutory scheme before the Court
The Court invalidated the challenged regulations as inconsistent with the congressional mandate it discerned and reversed the Fifth Circuit. The decision addressed particular in-kind benefits furnished for the employer's convenience, not every reimbursement, cash allowance, or fringe benefit. It also did not establish that calling an arrangement convenient satisfies section 119.
Justice White dissented, joined by Justices Brennan and Marshall. The disagreement concerned the significance of the statutory wording and longstanding administrative treatment. The majority's statutory premise, rather than the broad proposition that all tax bases are identical, is essential to understanding both the result and the later legislation.
What the decision means for taxpayers
Current section 3121(a) states that a withholding-regulation exclusion does not require a similar FICA-regulation exclusion. Section 3306(b) contains the corresponding FUTA provision. These later statutory provisions defeat an unrestricted use of Rowan's conformity rationale today.
The same current statutes expressly address meals and lodging: sections 3121(a)(19) and 3306(b)(14) exclude their value when, at furnishing, it is reasonable to believe the employee can exclude the items under section 119. Thus, recognizing the statutory change does not mean qualifying meals and lodging are necessarily taxable. The modern result rests on the applicable exclusion and its conditions.
Review the facts and each tax consequence separately
A present employer should identify whether the benefit is in kind or cash, where it is furnished, why the business needs it, and whether lodging must be accepted for proper performance of duties. Employee status and special ownership rules also matter. The current IRS fringe-benefit guide describes these distinctions.
See proving the job-related need for employer housing for the practical records task. Our tax-professional guide and tax-services page address assistance with that review. Rowan remains instructive about reading the statutory base, but quoting its 1981 result without the subsequent statutory changes would mislead a reader about present payroll law.
Frequently asked questions
Does Rowan make every income-tax exclusion a FICA exclusion?
No. Current sections 3121(a) and 3306(b) expressly reject automatic conformity based on withholding regulations.
Can qualifying meals and lodging still be excluded?
Yes. Current statutes contain specific exclusions tied to a reasonable belief that the employee can exclude the benefits under section 119.
Did Rowan concern ordinary cash housing allowances?
No. It concerned meals and lodging furnished for employees working on offshore rigs.
Apply the current statutory exclusion rather than a historical shortcut
Mishra X Trial Lawyers can help assess the available procedure using your specific documents. Call (949) 343-9735 or email office@mishrax.com.